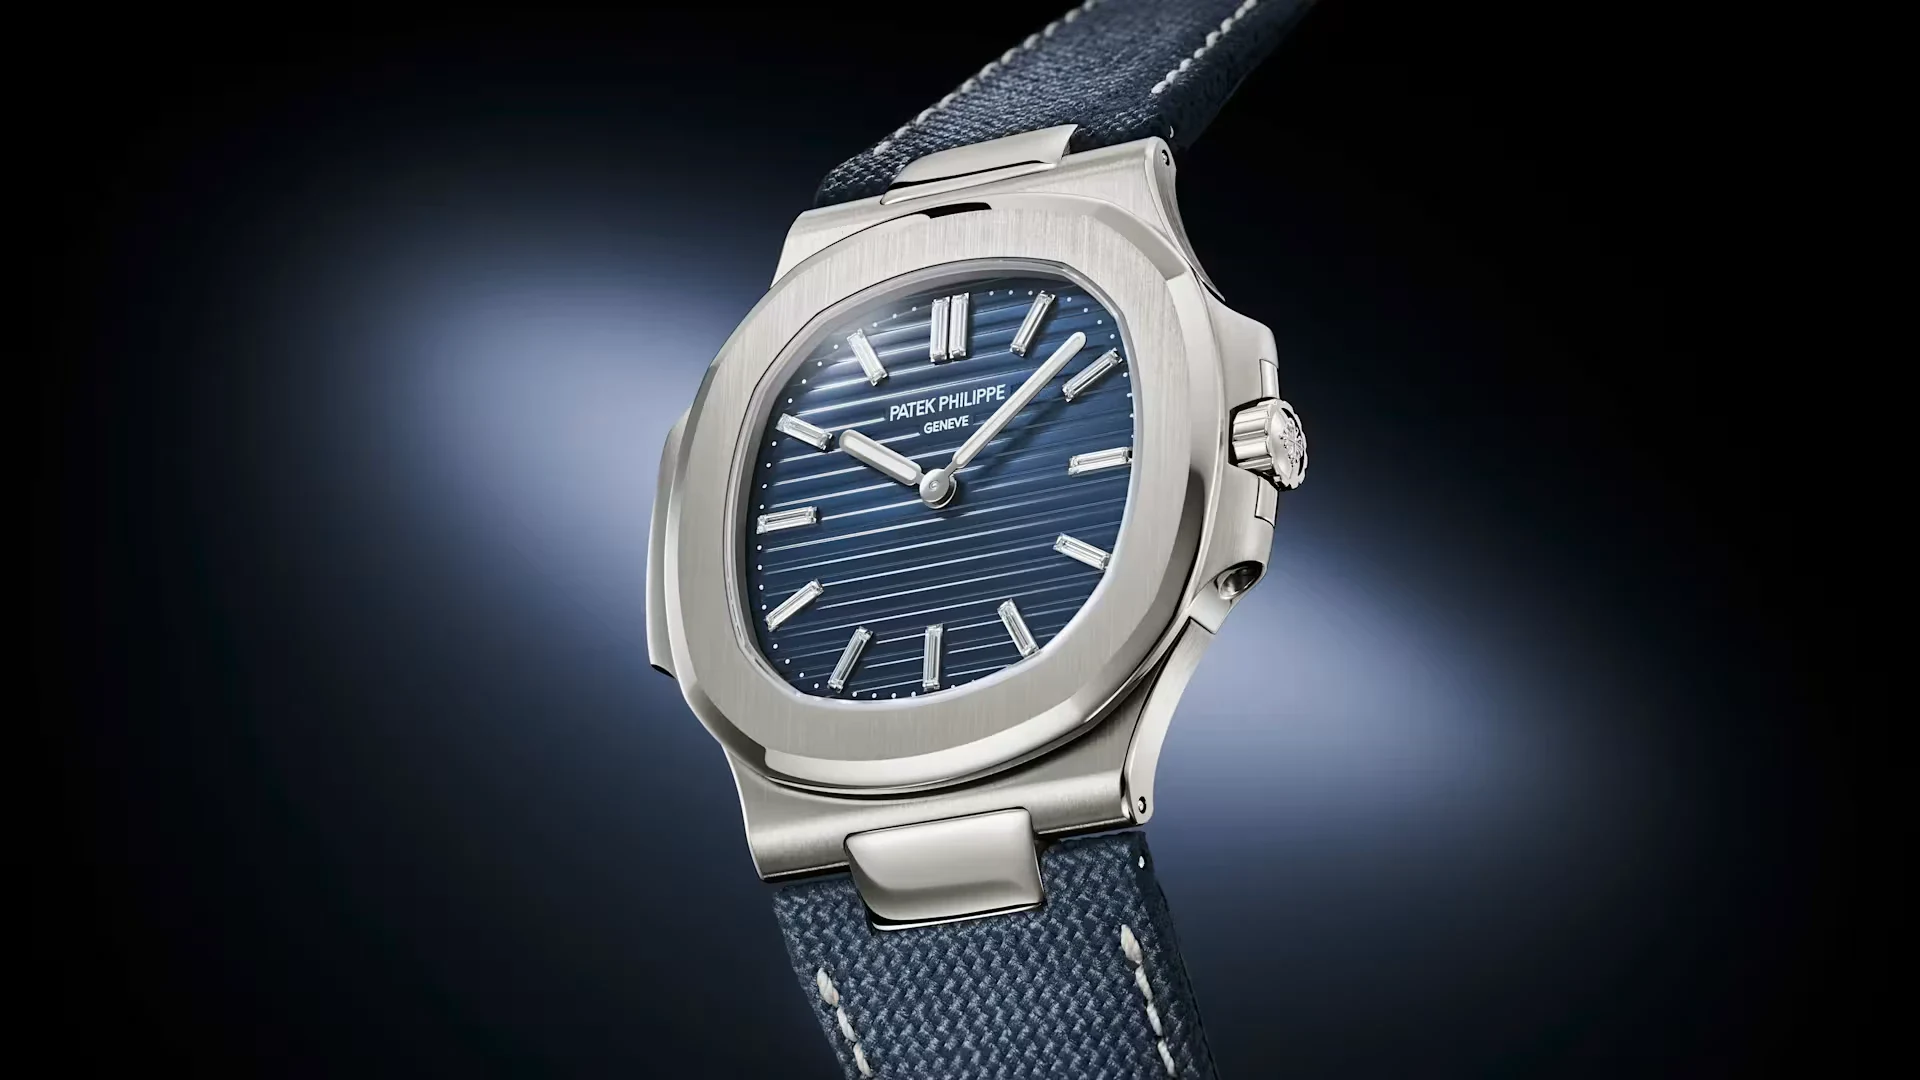
Vacheron Constantin posted the biggest rise in luxury watch values on the secondary market in 2026, according to Chrono24’s Q3 Quarterly Dial, published October 20. Its prices rose 6.7% in the third quarter and 17.7% over twelve months, just ahead of Patek Philippe at 17.0%. Audemars Piguet added 2.0% in the quarter, while Rolex slipped 0.2%.
Over the twelve months to September 2026, Vacheron Constantin rose 17.7% and Patek Philippe 17.0% on Chrono24's ChronoPulse Index. Audemars Piguet gained 2.0% in Q3, Rolex slipped 0.2%, and Hublot was the only tracked brand down year over year.
The wider market kept climbing, if quietly. Chrono24’s ChronoPulse Index, which follows secondary-market prices across 13 major brands and more than 140 references using transactions on its own marketplace, rose 0.7% between July and September to close at 1,471 points. It was the fourth positive quarter in a row, following gains of 2.8% in Q1 and 1.9% in Q2, and it leaves the index up 7.5% over twelve months.
That is the highest reading in three years, and the index touched a 52-week high of 1,477 points in August. In my view, the more telling number is how calm the climb has been. Chrono24 describes the year as steady, stable growth rather than sharp swings, a different market from the one collectors remember from the boom.
Where Luxury Watch Values Climbed Fastest
Vacheron Constantin led the index over three, six, and twelve months, gaining 8.2% over six months on top of its 6.7% quarter. The Maison closed September at a 52-week high of 1,670 points, 67.0% above its January 2019 baseline. Patek Philippe ranked second over both six and twelve months, adding 3.0% in Q3 and 5.8% over six months to finish at its own 52-week high of 2,086 points.
Patek’s year came with a familiar engine. Chrono24 says three steel Nautilus references ranked among the index’s best performers over the past twelve months, though the release does not name them. Balazs Ferenczi, head of brand engagement at Chrono24, calls the pairing at the top “a notable result,” adding that collector demand “is spreading across a few brands with strong design identities.”
Jaeger-LeCoultre ranked fourth over twelve months, up 11.0%, with 1.2% in the quarter and 2.3% over six months. Chrono24 singles out the Reverso, whose run tracks the broader return of square cases; four of the ten best-performing watches of the past year have one. Audemars Piguet, the third Holy Trinity house, gained 2.0% in Q3 and posted gains over three, six, and twelve months.
Rolex Holds Its Ground
Rolex barely moved in the quarter, slipping 0.2%, but the longer view is firmer than that number suggests. The brand gained 2.2% over six months and remains 6.0% above its level of a year earlier. For the market’s largest name, a flat quarter after a strong first half reads to me more like a pause than a retreat, and the twelve-month figure supports that.
Hublot was the only tracked brand to decline over twelve months, and Chrono24 does not publish its percentage. The release gives no figures for Richard Mille, Blancpain, or F.P. Journe, so this index cannot say how they fared. Chrono24 also notes that month-to-month data for lower-volume brands can swing more sharply, which is worth remembering before reading too much into any single quarter.
The full brand-by-brand breakdown is in Chrono24’s Q3 2026 Quarterly Dial, which converts every transaction into euros at the rate on the day it closed. The message for collectors is plain. After years of correction, the secondary market is rising again, and this time two of the oldest names in Geneva are setting the pace.
Timely FAQs
Which luxury watch brand gained the most value in 2026?
How much did Patek Philippe prices rise in 2026?
Did Rolex prices go up in Q3 2026?
What is the ChronoPulse Index?
